Utah Tenant Screening That Protects Apartment Value
Utah tenant screening protects occupancy and income when owners use consistent criteria, verify risk, and make faster, fairer leasing decisions every day.
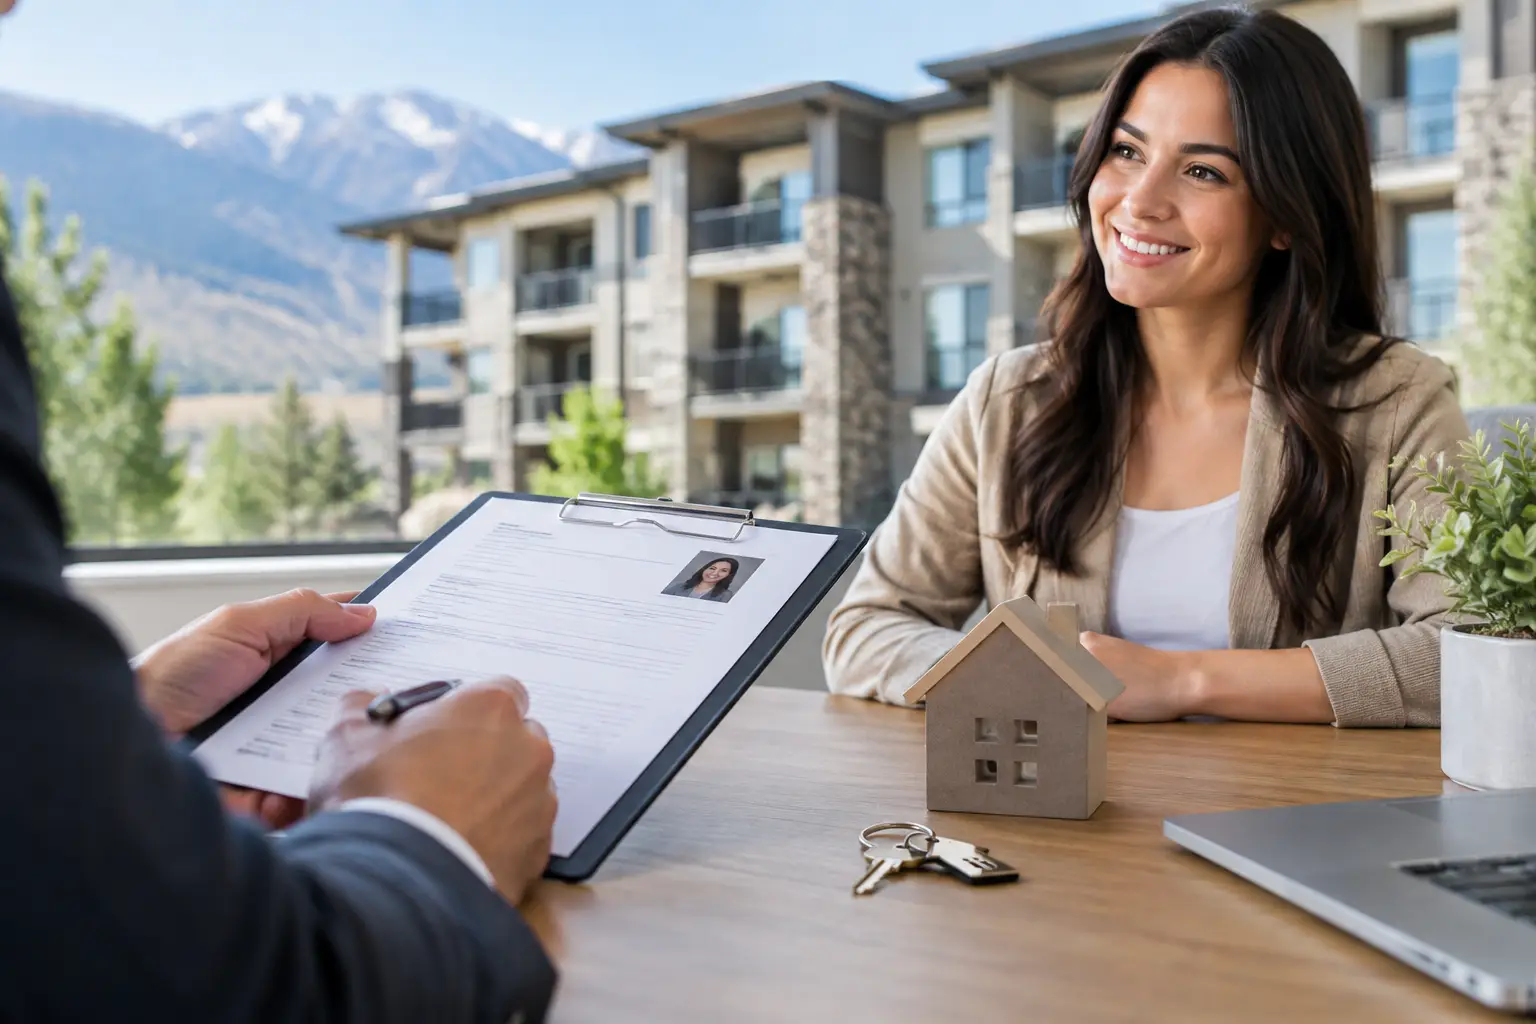
A vacancy is expensive. A poorly screened placement can be more expensive still – particularly when it leads to missed rent, repeated lease violations, avoidable turnover, or a unit that returns to make-ready condition before the original leasing costs have been recovered. Utah tenant screening is not a back-office task. For apartment owners, it is an operating control that protects income, resident experience, and the long-term value of the asset.
The goal is not to find a flawless applicant. Very few applicants have a perfectly linear rental or credit history. The goal is to apply clear, lawful, consistent standards that identify a resident who can meet the lease obligation and contribute to a stable community. Done well, screening supports occupancy without sacrificing discipline.
Why Utah Tenant Screening Is an Owner-Level Decision
Screening decisions shape more than delinquency reports. They affect the workload placed on onsite teams, the frequency of unit turns, maintenance demand, collections costs, and the experience of residents who pay reliably and expect a well-managed property.
Owners sometimes respond to vacancy pressure by lowering standards informally. A leasing agent may be encouraged to “make it work” for an applicant with incomplete income documentation, a vague rental reference, or unresolved credit concerns. There are situations where an approved exception may make sense, but exceptions without a documented framework create risk. They can lead to inconsistent treatment, weaker collections, and a resident profile that does not support the property’s business plan.
The opposite mistake is screening so rigidly that qualified applicants are lost to competing communities. In Wasatch Front submarkets with active apartment supply, response time matters. A sound process should give the leasing team enough structure to make decisions quickly while reserving true judgment calls for management review.
Start With Written, Property-Specific Criteria
A screening policy should be written before an application arrives, not adjusted after a team likes or dislikes a particular applicant. It needs to reflect the community’s rent level, unit mix, resident profile, historical delinquency, and the owner’s tolerance for risk.
At a minimum, criteria commonly address verified household income, credit history, rental history, identity verification, criminal background review where legally appropriate, occupancy limits, and the documentation required from applicants. The standards should state what produces approval, conditional approval, denial, or a request for additional information.
The value of written criteria is consistency. Leasing staff know how to move an application forward. Applicants receive a clearer process. Ownership has a record of how decisions are made across the property. That structure matters when staffing changes or when a busy leasing season puts pressure on the team to make quick decisions.
Income requirements deserve particular attention. A simple income multiple can be useful, but it is only as good as the verification behind it. Recent pay stubs, employer confirmation, tax records for self-employed applicants, benefit statements, and bank documentation may each be appropriate depending on the situation. A stated income figure is not verification.
For properties serving a broad range of household types, a practical policy also defines how to evaluate nontraditional income and guarantors. That prevents staff from improvising under pressure and helps ensure similarly situated applicants are treated consistently.
Credit Is a Risk Signal, Not the Entire Decision
A credit report can reveal unpaid housing debt, recent collections, payment patterns, and obligations that may affect a household’s ability to pay rent. It does not, by itself, explain every financial event. Medical debt, a temporary job interruption, or an older issue that has since been resolved may require a closer look under the property’s stated standards.
The most useful approach focuses on the factors that directly relate to lease performance. Prior unpaid rent, housing-related collections, recent evictions, and repeated late payments generally deserve more weight than an isolated, unrelated credit issue. Owners should avoid a vague process where one staff member overlooks a concern and another rejects an applicant for the same circumstance.
Conditional approval can be a practical middle ground when it is applied under established criteria. A qualified guarantor, higher deposit where permitted, or another documented risk-control measure may allow the property to capture a viable lease without ignoring the underlying concern. The terms must be consistently administered and reviewed for compliance with applicable law.
Verify Rental History Before It Becomes a Turn Cost
Rental references often provide the most useful operational information in an application. A prior landlord may confirm payment performance, lease compliance, notice history, property condition at move-out, and outstanding balances. But a reference is only meaningful when the source is verified.
Calling a number supplied by the applicant without confirming it belongs to the actual housing provider leaves room for false references. A disciplined team uses independent contact information when possible, documents the conversation, and asks the same relevant questions for each applicant. If a former landlord cannot provide details, that should be recorded rather than filled in with assumptions.
Owners should also distinguish between a difficult resident and a resident who simply moved during a lease-up, job relocation, or family change. Frequent moves can be a concern, but context matters. The screening file should support the decision with facts, not impressions.
Speed Matters, but Shortcuts Cost More
The strongest leasing teams treat application follow-up as a timed operating process. They acknowledge a completed application promptly, identify missing documentation quickly, and communicate the next step without leaving the applicant guessing for days.
Delay has a measurable cost. A qualified prospect may lease elsewhere, while an applicant with a weak file may receive approval simply because the team is trying to fill a vacant unit. Neither outcome serves the owner.
A practical workflow includes an application completeness check, identity and income verification, screening report review, rental-history confirmation, management review of exceptions, and documented final notice. The exact sequence can vary, but accountability should not. Every file needs a clear status, an assigned owner, and a defined next action.
Technology can help organize documentation and reduce manual errors, but it does not replace management judgment. A report may flag information that is outdated, incomplete, or not relevant under the property’s criteria. Conversely, an automated approval should not excuse a team from verifying that the file is complete.
Fair, Defensible Decisions Protect the Property
Tenant screening must be administered in compliance with fair housing requirements, consumer reporting rules, and applicable state and local requirements. Owners should work with qualified legal and compliance professionals to establish criteria, notices, adverse-action procedures, record retention practices, and policies for reviewing criminal history or other sensitive information.
From an operating standpoint, the central discipline is straightforward: apply the same written standards to every applicant, document exceptions, and avoid subjective commentary in the file. Decisions based on rumors, personal familiarity, or a leasing agent’s instinct are difficult to defend and inconsistent with professional asset management.
Training is part of the control system. Staff need to understand what they may request, how they should handle applicant information, when a file requires escalation, and how to communicate a decision professionally. A policy stored in a shared folder but not used in daily leasing work does not protect the owner.
Review Screening Performance Against Property Results
A screening policy should not remain static indefinitely. Owners should periodically compare approvals, conditional approvals, denials, delinquency, skips, lease violations, evictions, renewal rates, and turnover costs. The purpose is not to chase a single metric. It is to determine whether the current process is producing stable occupancy and dependable revenue.
If delinquency is climbing among recently approved residents, the income verification process may be too loose or exceptions may be poorly controlled. If qualified traffic is repeatedly lost, response times or criteria may need review. If certain units experience repeated early move-outs, screening may be only one part of the problem – unit condition, maintenance response, pricing, and resident communication also deserve scrutiny.
At Concept Multifamily, screening is viewed as part of a larger operating system. The lease file, resident experience, maintenance follow-through, curb appeal, and capital plan all influence whether an apartment community produces durable cash flow. No screening process can compensate for poor operations, but disciplined placement gives good operations a far stronger foundation.
A well-screened resident is not simply an approved application. It is a better chance at on-time rent, a completed lease term, a smoother renewal conversation, and fewer preventable disruptions to the community. That is the standard worth building into every leasing decision.
Share this article
Follow us
In this post
Latest posts
November 20, 2026
November 20, 2026
November 20, 2026
Subscribe
Subscribe below to receive the New Concepts newsletter: insights on property management, investing, and the industry